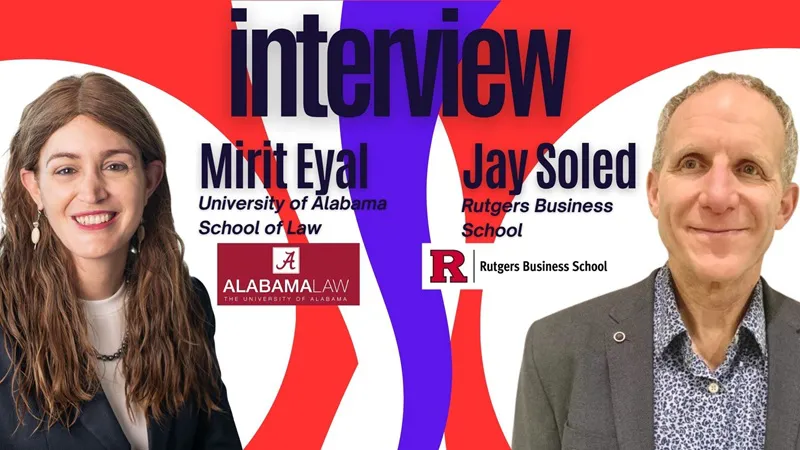
By Tatiana Martins, journalist at G&M News.
Your paper argues that most retail activity in prediction markets should be treated as gambling rather than investment for tax purposes. What are the main economic and behavioral factors that led you to this conclusion?
First, consider the economics involved. Most event contracts do not give the holder ownership in a productive enterprise or a claim to future business income. Instead, they create a contingent right to a payout if a prediction proves correct. Participants are not investing capital in a business. They are betting on whether an uncertain event will occur, based on the belief that they know more than the person on the other side of the trade. Like a sports bet, the participant puts money on an uncertain future event, and the payout is either a win or a loss. The two often cover the same events, especially sports. The evidence on outcomes points the same way. Most retail accounts appear to lose money after fees, and profits are concentrated in a very small group of traders. One analysis of Polymarket found that about 70 percent of addresses had realized losses, while fewer than 0.04 percent captured more than 70 percent of the profits. The behavioral picture reinforces this. These products deliver excitement, suspense, and the thrill of being right, much as gambling does. Artificial intelligence and platform design make that stronger by personalizing wagering opportunities, speeding up trading, and blurring the line between entertainment and investment.
One of the key arguments in the paper is that the economic function of a transaction should matter more than the platform’s terminology. How should regulators determine whether an event contract represents a genuine investment, a hedge, or a consumption-oriented wager?
Our answer is to look at the substance rather than self-serving labels. The platform’s vocabulary may decide how a product is marketed, but its economic function should ultimately decide how it is taxed. A regulatory label is relevant evidence, but it does not settle the income-tax question. The CFTC’s October 9th, 2026, actions illustrate the point. The agency tried to separate federally regulated event derivatives from conventional gambling by form and venue, not by economic function, and it didn’t address income tax at all. We propose a sliding-scale approach that considers the contract’s duration, whether the holder faces an objectively identifiable risk, and the holder’s activity, volume, and economic purpose. A short-dated contract on a game or an election, held by someone with no offsetting exposure, looks like a recreational wager. A longer-dated contract that reduces risk the holder already has looks like a hedge. Proof matters. A hedge should be identified and documented upon entry. Casual users should not be able to label themselves hedgers, and the taxpayer claiming the exception should bear the burden of showing that it applies. Neither sophistication nor heavy trading should qualify anyone on their own.
The document proposes taxing retail event contract winnings as ordinary income while generally disallowing associated losses. What would be the main practical and economic implications of this approach for prediction market users and the platforms themselves?
We should first clarify that the paper treats two policy choices separately. The first is parity: comparable retail wagering should face the same tax treatment whether it takes place on a sportsbook or an exchange. The second is how losses should be measured, and agreeing on parity does not settle what percentage of losses should be deductible. The more modest path would extend today’s gambling-loss rule to event contracts. For tax years beginning in 2026, that rule allows a deduction for 90 percent of wagering losses, capped at wagering gains. The broader path would disallow losses altogether for both event contracts and traditional gambling, drawing on the tax law’s treatment of hobby losses and business entertainment. For users, gains would be taxed at ordinary rates of up to 37 percent rather than at the long-term capital-gains rate of 20 percent, and recreational losses could not be used to shelter unrelated income. We take seriously the strongest objection: that someone with offsetting gains and losses could owe tax despite having no net economic gain. We also note that the current gambling rules already treat taxpayers unevenly. Only itemizers can deduct losses; about 91 percent of returns claimed the standard deduction in 2022, and gambling winnings can reduce the Earned Income Tax Credit for low-income participants. For platforms, the main consequence is competitive. They would lose a tax advantage over sportsbooks that rest only on regulatory form, and they would need much better record-keeping, including cost basis, proceeds, fees, year-end positions, and hedge designations. For governments, federal receipts would likely rise. As a rough illustration, USD 100 billion of winnings would generate up to USD 37 billion in tax at ordinary rates, compared with USD 20 billion at long-term capital-gain rates. States would also protect the gaming-tax revenue on which many of them rely.
Prediction markets are expanding into areas beyond sports, including politics, economics, weather and other real-world events. Does your proposed tax framework apply equally across these different types of contracts, or are there categories that require different treatment?
The principle applies across the board, but the results depend on function rather than subject matter. Most contracts on elections, sports, or cultural events, held by participants with no offsetting exposure, resemble recreational wagers. Weather and macroeconomic contracts can be different when a business uses them for genuine risk management. A farmer managing temperature risk for crops, or a company protecting temperature-sensitive revenue or hedging against energy price spikes, gets less entertainment value and more business value. That supports a narrow, well-documented hedging exception. Even so, the subject is not decisive. The same weather contract bought casually by a retail trader is still a wager. We also flag contracts that settle on conduct a participant can influence, such as so-called mention markets, as raising separate manipulation concerns. Applying the framework to contracts that have not yet settled to portfolios with offsetting positions, and to payouts that are not strictly binary remains an important area for further research.
What do you believe policymakers and prediction market operators should focus on next to create a clearer and more consistent tax framework for event contracts, particularly as these markets continue to develop in the United States?
Congress should act directly rather than wait for the preemption litigation to play out. The federal circuits are now split, and a petition for certiorari is pending before the Supreme Court. The tax rule should rest on economic function and should work the same way, regardless of how those cases are resolved. So far, the IRS has issued no published guidance on whether modern event contracts are wagering transactions, capital assets, or Section 1256 contracts. A workable statute should define covered retail wagering by objective features rather than platform branding. It should also explain how the new rule interacts with the capital-asset, Section 1256, mark-to-market, and wagering-loss rules, and it should address basis recovery, netting, early exits, fees, and trading across platforms. Exceptions should be limited to proven hedging and market-making, and the statute should set a clear effective date and phase in the new reporting requirements. Congress should also coordinate the income-tax rule with reporting, withholding, the federal wagering excise tax, and state gaming taxes. For operators, the priority is consistent, accurate reporting of information. Today, the reporting landscape is fragmented, and tax compliance tends to drop sharply when no information return is issued. Finally, we need an empirical study of whether different tax treatments affect market liquidity, price accuracy, and participant behavior.